The Bottom Line
- Indonesia is the biggest market, but the door is basically closed. The RMB 21.1B monthly market is flat, Shopee Indonesia is the only "extreme" competition tier among the six sites, and only 211 new sellers entered in the past 90 days while 157K exited. This isn't a blue ocean or a red ocean — it's a stock meat grinder.
- Thailand is the only site with "low friction + high ticket." Shopee Thailand sellers have a 90.2% 90-day survival rate and a 9.8% churn rate (lowest of six sites), RMB 51 average ticket (highest of six sites), and +33% market growth. Stability is this site's defining trait.
- Vietnam offers the best combination of growth and competition density. Market up +44% (highest of the three), 450K sellers across both platforms (less than 40% of Indonesia's), and TikTok sellers average RMB 40K monthly output — fewer sellers, more money.
- So how to pick your first market depends on what kind of brand you are: supply-chain players go to Vietnam, content players go to TikTok Thailand/Vietnam, cash-flow players go to Shopee Thailand. Indonesia isn't your first stop — it's your second, once you have winning products and cash flow to harvest its scale.
1. What Are You Really Choosing When You Choose a First Market?
Most people talk about "first market" in terms of how big a market is and whether it's growing. Both matter — but that's only half the answer.
What you're really choosing is the pool your money and team fall into during the cold-start period. That pool has three cards on the table:
- Scale (how big is the pool, where's the ceiling)
- Growth (is the tailwind still there, who captures the dividend)
- Competition density (how many people are fighting you, and are they doing well)
The third card is the easiest to overlook — and the most life-or-death for cold starts. A RMB 20B pool crowded with 1.2M sellers versus a RMB 15.5B pool with only 450K sellers: two completely different worlds for a new brand.
First, scale and growth. In September 2026, Shopee + TikTok Shop across Indonesia, Thailand, and Vietnam totaled about RMB 56 billion:
By country: Indonesia RMB 21.1B (≈flat), Thailand RMB 19.5B (+33%), Vietnam RMB 15.5B (+44%).
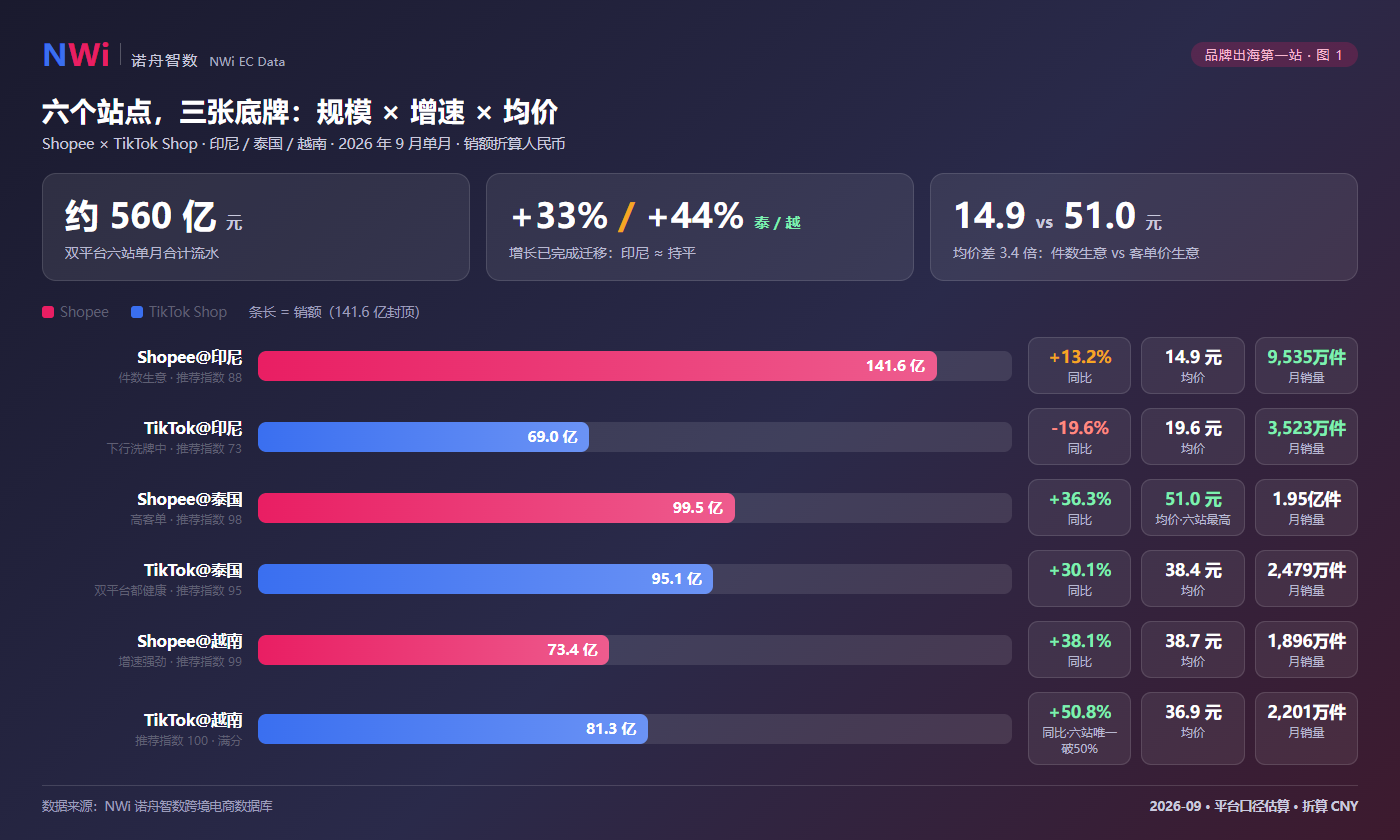
Second, average ticket differs 2–3×. Indonesia's 15–20 RMB is a volume business; Thailand/Vietnam's 37–51 RMB is a ticket-size business. This determines whether your cost structure, logistics plan, and even pricing logic can be reused across markets.
But looking only at those two cards will get you the wrong answer. The third card is what really separates the options.
2. Indonesia: The Biggest Pool, with the Door Basically Closed
We ran a seller ecosystem snapshot across the six sites (single month, with a 90-day entry/exit window). Indonesia first:
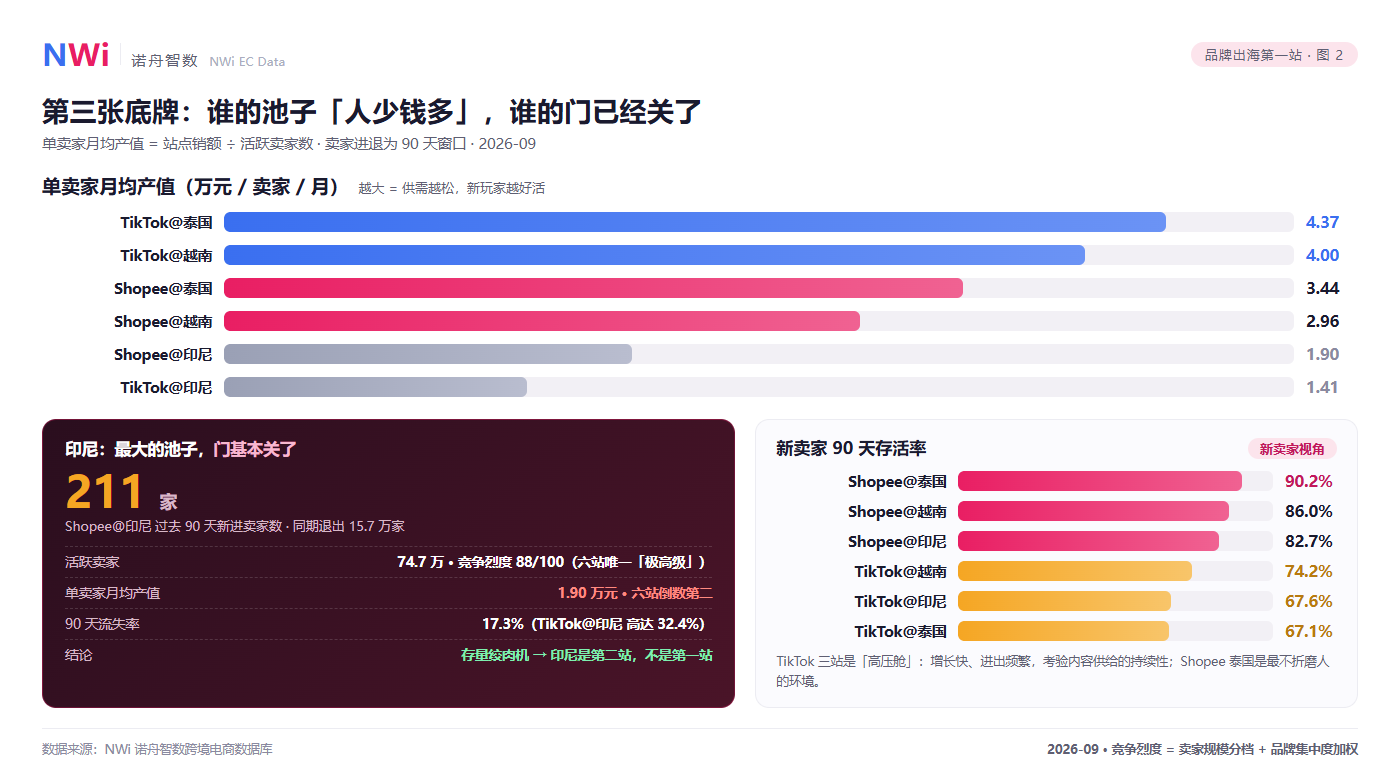
Shopee Indonesia's 747K sellers fight over RMB 14.16B in a month — RMB 19K output per seller per month. What does that mean? After commissions, logistics, and ads, most sellers' net profit can't sustain a five-person team. And in the past 90 days, only 211 new sellers entered — not because nobody wants in, but because traffic allocation and category structure have solidified; the cold-start economics of a new store simply no longer compute. The 157K exits in the same window are an organized, at-scale retreat.
TikTok Indonesia looks open on the surface (25.6K new sellers in 90 days), but with a 32.4% churn rate and the overall market at -19.6% — this is a battlefield in violent reshuffling and downtrend, not a place to bet your cold start.
3. Thailand: The Most Balanced "Cash-Flow Market"
Look at Thailand's two tables together:
- Thailand is the only market where both platforms are healthy. Shopee and TikTok sales are nearly tied (9.95B vs 9.51B), both growing 30%+. That means you can run dual-platform there — creative assets, product mix, and local resources all reusable at near-zero marginal cost.
- Shopee Thailand is the only "low-friction" pool among the six sites. 9.8% churn, 90.2% new-seller survival, "high" competition tier but brand concentration CR5 of just 21.8% (most fragmented top players). For brands needing stable cash flow, this is the least torturous environment.
- RMB 51 ticket size creates room for brand premium. Highest of the six sites, 3.4× Indonesia's. Mid-to-high ticket categories have pricing headroom here — no fighting to the death in the RMB 15 band.
Thailand's weakness is also straightforward: competition is not low (3,000 entries/90 days vs 31K exits), and Thailand's e-commerce infrastructure and payment penetration are the most mature of the three — the dividend period started earliest and is the least glamorous. What it offers isn't a boom; it's compounding.
4. Vietnam: The Highest-Growth, Fewest-Sellers "Aggressive Market"
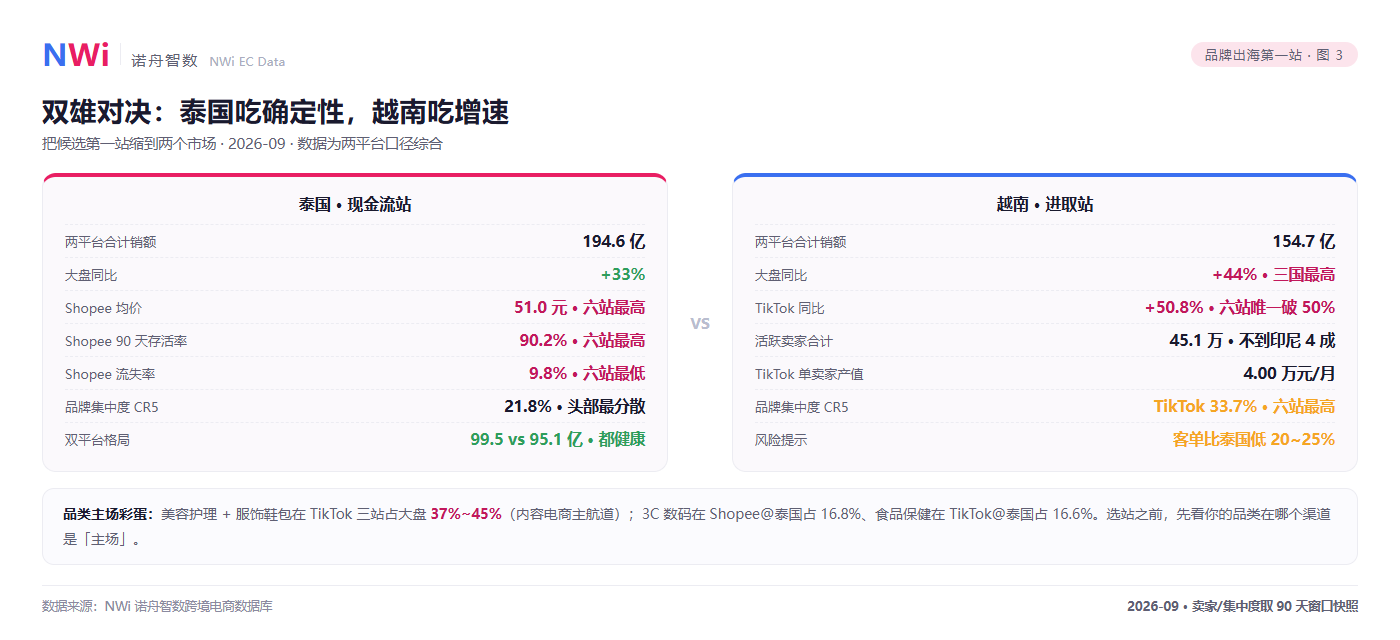
Vietnam's structural advantage in one sentence: the denominator of its growth hasn't piled up yet.
Market +44% — highest of the three countries; TikTok +50.8%, the only site breaking 50% across six sites; 450K sellers on both platforms combined, less than 40% of Indonesia's. TikTok Vietnam's per-seller monthly output is RMB 40K, second only to TikTok Thailand — a pool of 200K sellers doing RMB 8.1B in monthly sales, and still growing at 50%.
Two reminders:
- TikTok Vietnam has the highest top-brand concentration of the six sites (brand CR5 = 33.7%). This market has already produced a batch of true leading brands — new brands entering need a real differentiation weapon, not brute-force listing.
- Vietnam's ticket size is the lowest among Thailand/Vietnam (RMB 36.9–38.7), 20–25% below Thailand. Supply-chain-cost-sensitive categories must factor this gap into their margin model.
5. Turn the Answer into a Decision Table
Now that the data is on the table, here's an executable decision table:
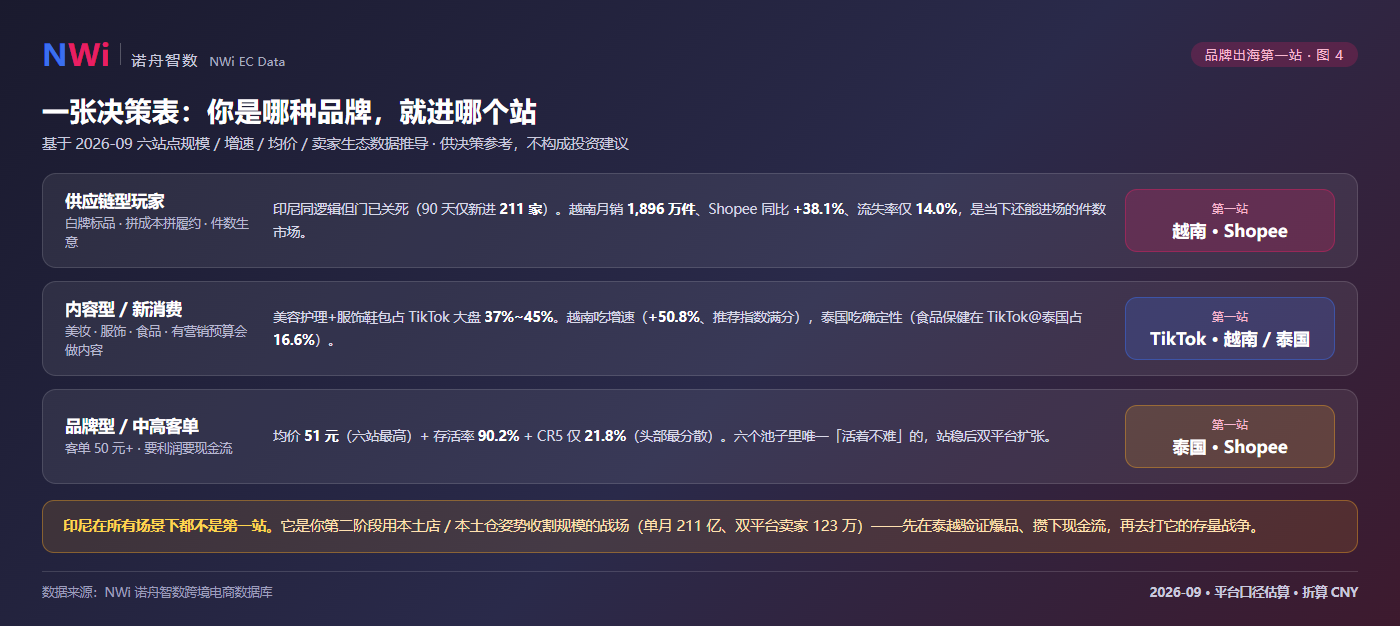
- If you're a supply-chain player (white-label standard products, competing on cost and fulfillment): first market is Vietnam Shopee. Indonesia's volume logic is identical but its door is shut; Vietnam's 190M units/month, +38% growth, and 14% churn make it the volume market you can still enter today.
- If you're a content/new-consumer brand (beauty, apparel, food — with marketing budget and short-video capability): first market is TikTok Shop in Vietnam or Thailand. Beauty & personal care plus apparel/shoes/bags take 37%–44% of those platforms' mix — the main channel of content commerce. Vietnam eats the growth (+51%); Thailand eats the certainty (food & health at 16.6% on TikTok Thailand, extreme content-led conversion).
- If you're a brand/premium player (RMB 50+ ticket, chasing margin and cash flow): first market is Shopee Thailand, then dual-platform expansion once established. RMB 51 ticket + 90% survival + 21.8% CR5 — the only pool of the six where "staying alive isn't hard."
One final category-view easter egg: for beauty, the category takes 16.1% on Shopee Vietnam but 18.2% on TikTok Vietnam — the content platform's structural premium is real. When choosing a market, first check which channel is your category's "home field."